

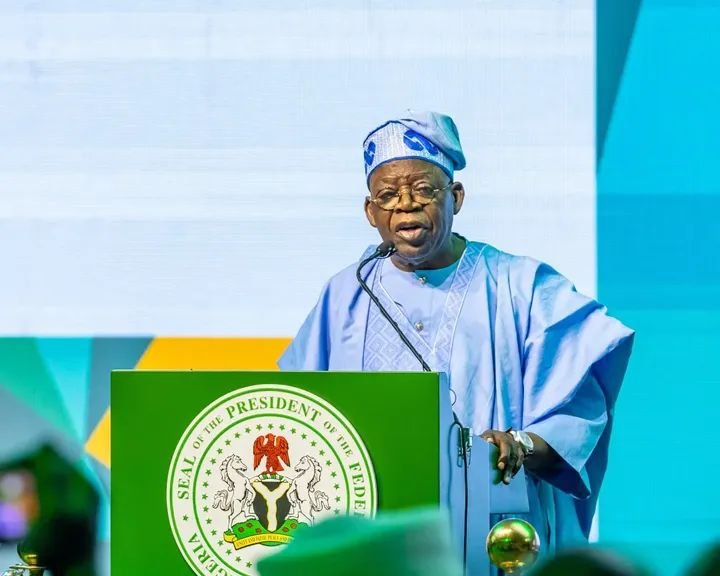
President Bola Tinubu on Sunday welcomed the World Bank’s latest Nigeria Development Update, stating that its findings, among them that the poverty rate, has stabilized for the first time since 2019 confirm his economic reforms are producing results.
In a Sunday statement issued by his Special Adviser on Information and Strategy, Bayo Onanuga, the President said the October 2026 edition of the report, titled ‘Beyond the Federal Purse: How Higher Revenues Reshaped State Priorities,’ demonstrated that the reforms were yielding results and placing the economy on a stronger footing for sustained growth.
He pointed to the bank’s expectation that poverty will decline steadily as gross domestic product expands faster than the population.
Per the report, the economy expanded by 4.2 per cent in the first half of 2026, compared with 3.9 per cent in the first half of 2025, even amid the effects of the conflict in the Middle East.
The bank forecasts growth to average no less than 4.4 percent between 2026 and 2028.
On prices, it noted that inflation dropped from 27.6 per cent in January 2025 to 15.2 per cent in December 2025.
Higher global fuel prices tied to the Middle East conflict have since slowed that decline, though the bank said it expects inflation to fall to roughly 12 percent by 2028.
The report further stated that the current account surplus climbed to $12bn, or 7.0 per cent of GDP, in the first half of 2026, up from $8.6bn a year before.
Gross external reserves rose from $45.5bn at the close of 2025 to $53.8bn by the end of August 2026.
The bank attributed the reforms introduced since 2023 to boosting federation revenues by 69 percent in real terms between 2023 and 2025, with states benefiting the most.
It said states channeled the additional resources into raising capital spending by 151 per cent in real terms over the same period, with most of the funds directed to roads and other transport, agriculture, energy, and housing.
According to the report, 29 of 33 states redirected spending towards economic infrastructure, while real social spending per person increased in every state except one.
It also discovered that internally generated revenue grew in real terms in 31 of 35 states; 21 states lowered their debt-to-GDP ratio between 2021 and 2025; and Nigeria’s overall public debt is projected to drop from 40.0 per cent of GDP in 2025 to 38.1 per cent in 2026.
Tinubu said the findings confirmed that “the difficult but necessary decisions to remove the petrol subsidy, unify the foreign exchange market, and strengthen fiscal discipline have raised revenues, stabilized the economy, and created fiscal space for every tier of government to invest in its people.”
“The dividends of reform are becoming visible,” he said, adding, “But more work remains to ensure they fully translate into better living standards for every household, starting with lower food prices and decent jobs for our young people.”
He stated that his administration would “stay the course of reform and redouble its focus on inclusive growth under the Renewed Hope Agenda.”
Tinubu made a commitment to continue broadening targeted cash transfers, noting that these had already benefited over 10 million households.
He further promised to speed up the introduction of Compressed Natural Gas, boost agricultural output, and enhance access to reasonably priced healthcare and quality education “so that the prosperity being created is shared by all.
President Tinubu called on state governments to spend their increased revenues “more prudently” and to give priority to projects that raise living standards along with the health and education of residents.
He praised the Economic Management Team, headed by the Minister of Finance and Coordinating Minister of the Economy, together with state governors and other stakeholders, for their collaboration in carrying out the reforms.
He said, “I assure Nigerians that the best is yet to come under the Renewed Hope Agenda 2.0, which will accelerate the delivery of shared prosperity for all Nigerians.